September was expected to be another record month for US investment-grade issuance, but volumes ultimately undershot forecasts.
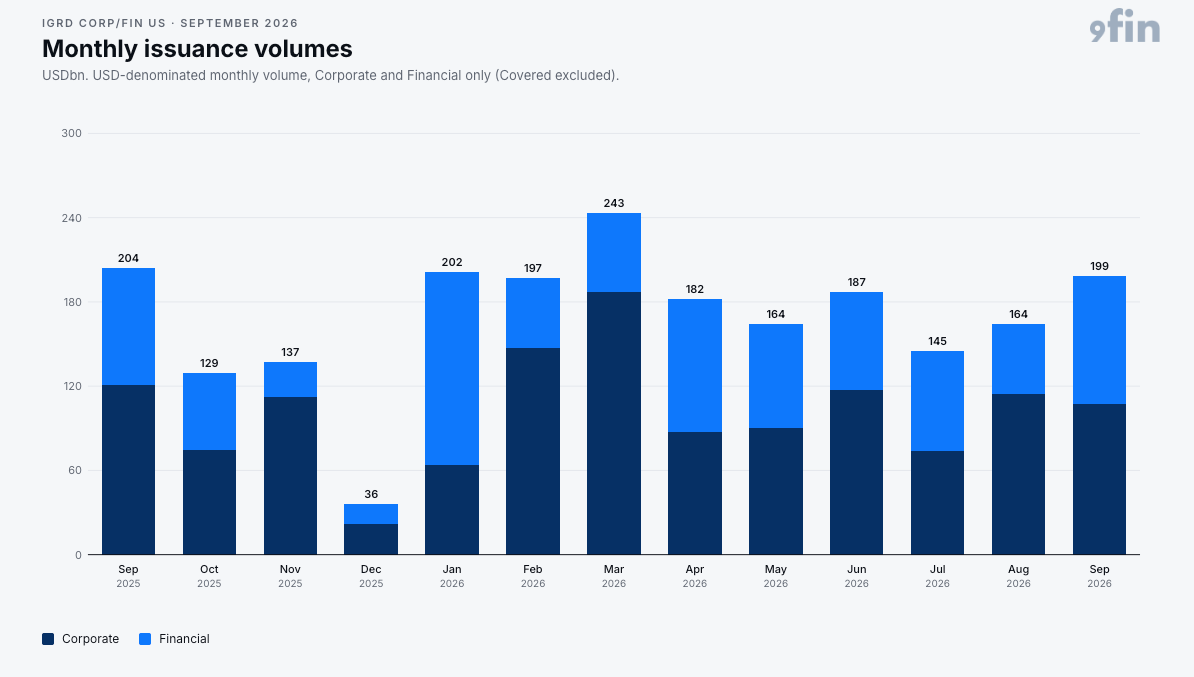
At $198.5bn, September is now the third largest month of the year to date, but total supply came in well below the $225bn one desk had pencilled in weeks earlier. Supply was broadly in line with the market’s $200bn average estimate, but supply was short of last September’s $204bn — an unusual miss in a year that has otherwise broken records almost every month.
The headline number also masks some of the changes happening in the asset class. A single $30bn megadeal from Paramount Skydance did the heavy lifting on the corporate side, league tables were reshuffled beneath the surface, and issuers quietly reversed a months-long drift toward longer maturities as Treasury yields pushed to multi-decade highs.
Source: 9fin
USD September issuance was split roughly 54/46 between corporates and financials, respectively, versus 59/41 in September 2025. September was shaping up to be a slower month, in part because a bigger August ($164bn) allowed issuers to pull forward supply and the later Labor Day had a larger-than-expected impact.
However, this was saved by Paramount’s $30bn print (30 Sept), which accounted for 28% of the...