Concerns over France's fiscal position showed no signs of easing this week. The OAT/Bund 10-year spread was hovering at around 170bps on Friday (23 October) morning, its widest since the Eurozone debt crisis in November 2011.
France was the exception in a week when most other sovereigns benefited from safe-haven demand. Investors sought shelter as AI fears continued to build and renewed geopolitical tensions pushed oil to a five-month high of almost $114/bbl.
Over the past week, 10-year US Treasury yields have fallen 15.4bps to 4.98%. Bunds are down 11.6bps at 3.34%, Gilts dropped 9.9bps at 5.33%, while Spanish 10-year yields fell 2.4bps to 4.04%.
Still, French fiscal worries fed into wider European credit conditions. The iTraxx Europe index, which tracks 125 investment grade corporates and financials, widened to 66.2bps from 64.9bps at the start of the week.
The backdrop weighed on primary activity. Euro issuance totalled just €20.06bn this week, down from €25.4bn last week, according to 9fin data.
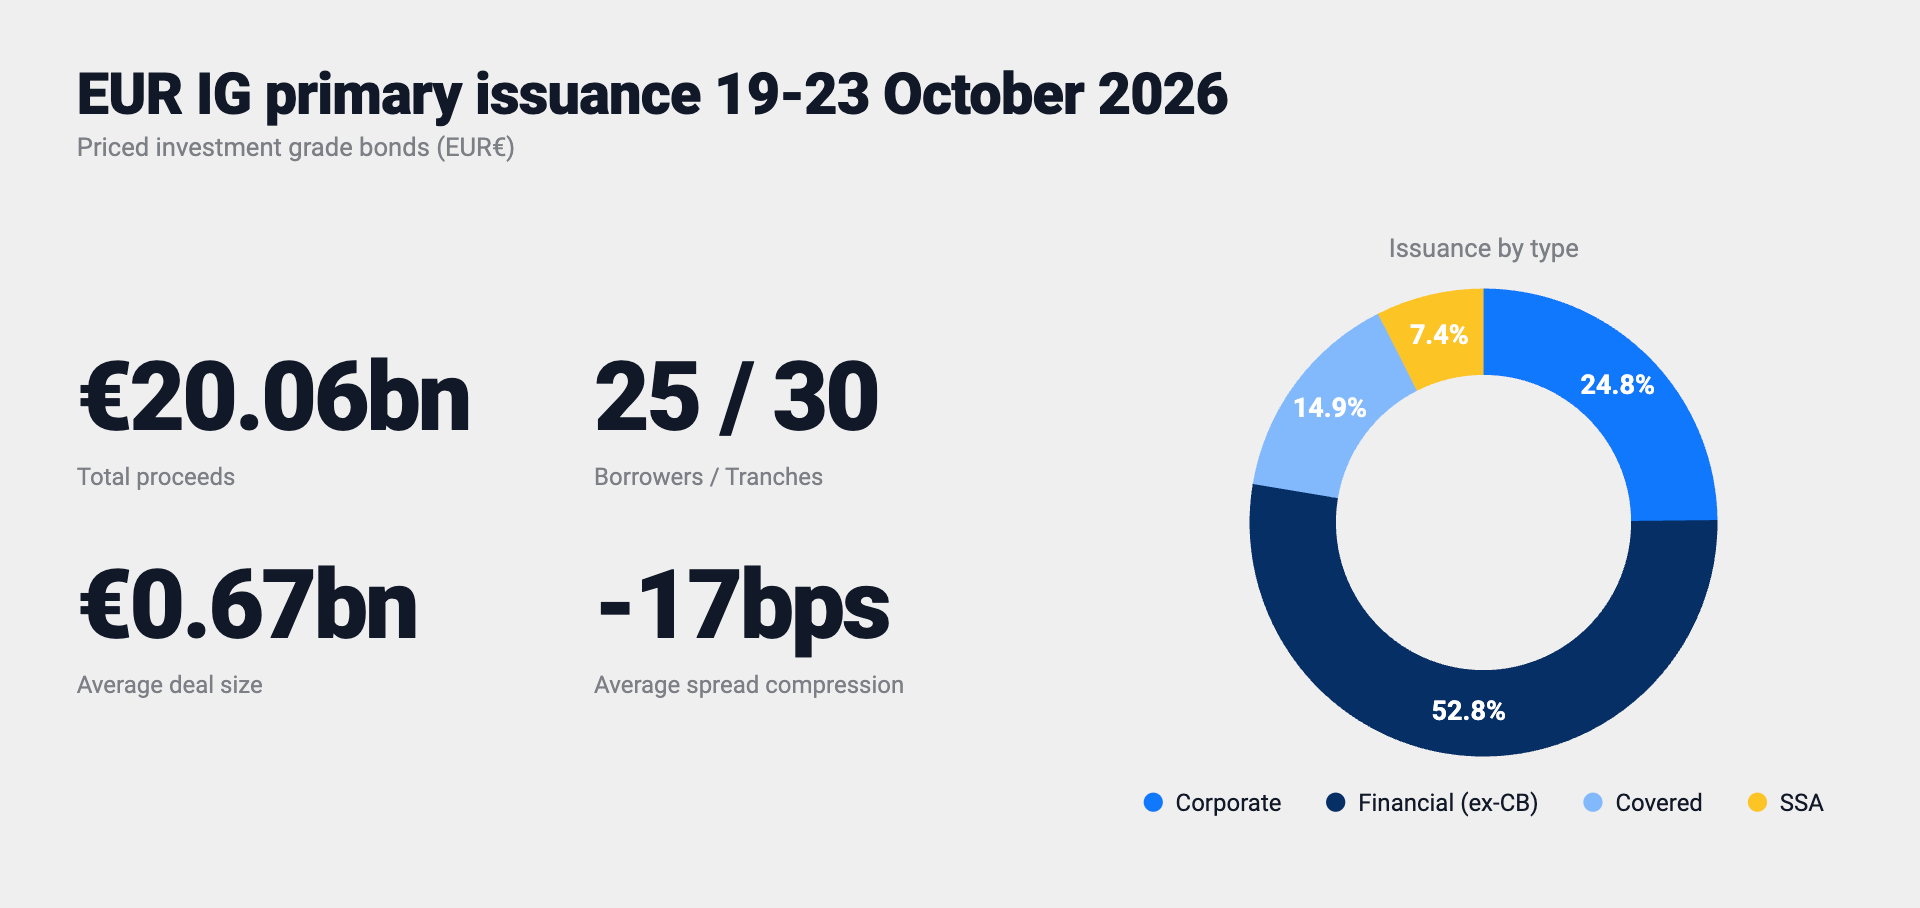
Financials (excluding covered bonds) were the most active sector at €10.6bn, followed by corporates at €3.5bn. SSA supply fell to just €1.5bn.
Corporate and SSA deals met softer demand, with cover ratios edging lower for both issuer categories compared to...