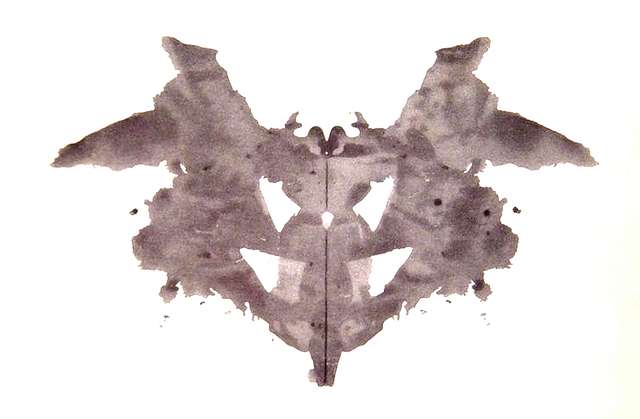
Is it a bat or a butterfly? As ever, it depends who you ask. Private credit has become a financial markets edition of the Rorschach test: for every declaration of health and explanation of a maturing asset class undergoing growing pains, there are fresh cockroaches unearthing themselves and further regulatory interventions warning of echoes with the 2008 GFC.
If we look to recent headlines, it does not get any clearer. HSBC is set to stop back-levering riskier private credit funds, institutional investors are plugging the gap of retreating retail clients in recent fundraises, while Hayfin closed its fifth direct lending vintage significantly over its €10bn target.
In the US, direct lending volume has sharply dropped alongside retail jitters among non-traded BDCs continuing into Q2 26 as the likes of Blue Owl, Apollo, Morgan Stanley, and Ares gate redemptions. While in APAC, Moody’s expects expansion to slow as Singapore’s Temasek seeks to double its private credit holdings over the next five years.
Some of this confusion can and has been explained: there is a clear bifurcation in fortunes for funds with predominantly institutional LPs versus those who pursued wealth clients in recent years.
“What...