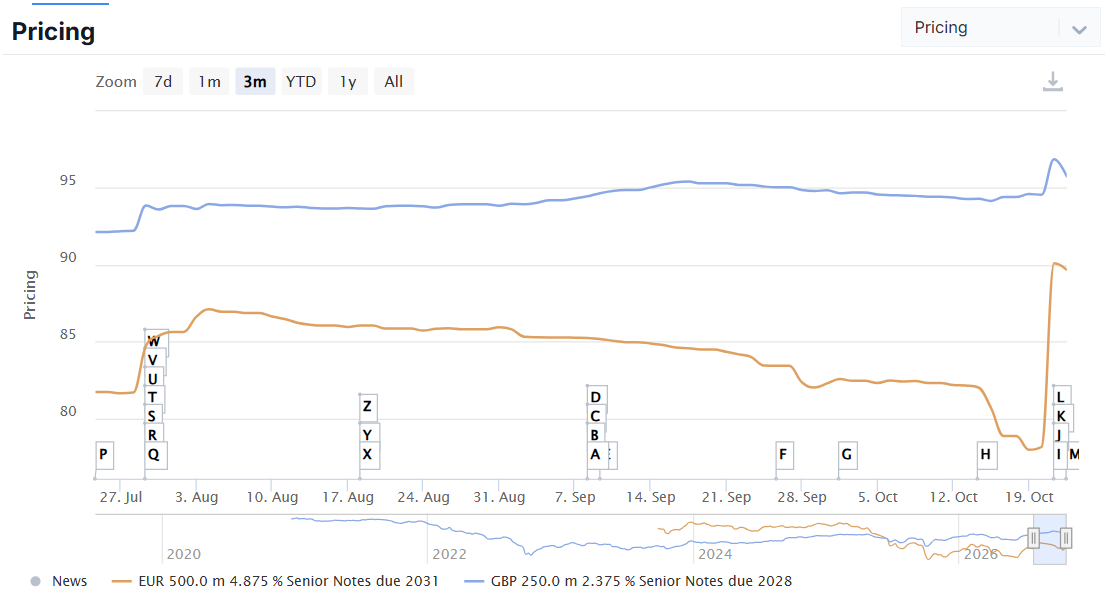
Mobico senior unsecured bonds have rallied on a 46p-per-share takeover approach, with some holders betting a successful deal would trigger a change of control (CoC) and repay them at par. On the 2028s and 2031s terms the bet looks well founded, because the final terms give holders a put at par. However, the £500m hybrid has no put: here par depends on the buyer choosing to call it.
The approach lands on top of a multi-year slide in Mobico’s credit quality. Mobico (formerly National Express) lost its investment-grade ratings over 2024-25 and now sits at B2 at Moody’s and BB at Fitch, after a disappointing sale of its North America School Bus business in 2025. It has kept shrinking since: in August it agreed to sell UK Bus to the West Midlands Combined Authority for about £24m.
To make matters worse, Deloitte resigned as auditor in September 2025, FY 25 levered FCF was a £111m outflow, and Alsa chief Paco Iglesias replaced Phil White as group CEO in March. Until the offer disclosed this week, Mobico was preparing a comprehensive refinancing plan for lenders, due as early as November, and weighing a debt raise at Spanish...