This quarterly update continues 9fin's analysis of EBITDA add-backs across European high yield. Find our previous reports for 2021, 2023, 2024, 2025 (Q1, Q2, Q3, Q4), and Q1 26 linked. 9fin also reviewed the broader trends seen in Q2 26 European bond primary here.
The second quarter added 46 euro- and sterling-denominated bond deals to our 2026 dataset, from each of which we have disaggregated their marketed EBITDA into five core categories: clean EBITDA plus non-cash items, exceptional items, cost synergies, revenue synergies, and other adjustments. A detailed methodology breakdown can be found here.
TLDR
Source: 9fin
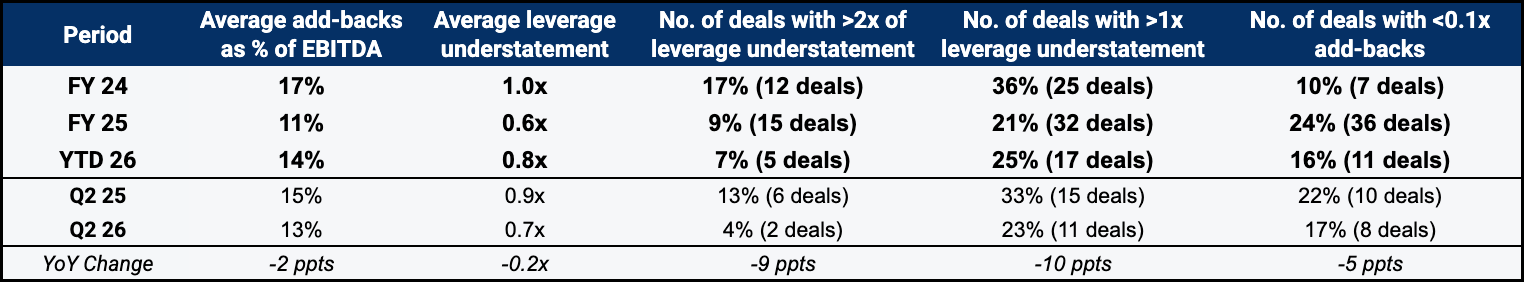
- Add-backs averaged 13% of marketed EBITDA in Q2 26, down from 15% a year earlier, while average leverage understatement narrowed to 0.7x from 0.9x
- Cost synergies reached an average of 3.7% of marketed EBITDA, the highest quarterly contribution in our series to date, as three corporate carve-outs replaced historical costs previously incurred as part of a larger group with new standalone cost assumptions
- Revenue synergies fell to 0.9%, from 1.7% in both Q1 26 and Q2 25, as growth assumptions gave way and exceptional items eased to 8% of marketed EBITDA. Only Avolta